
Key Development
Nearly VND2.35 trillion in cumulative net profit over four years is notable. More strategically important, however, is that Hoan My has simultaneously strengthened equity, eliminated bond debt and continued operating a network of nearly 3,000 beds.
Hoan My Medical Corporation reported VND679.4 billion in net profit for 2025, up nearly 23% year on year and its highest result since publicly reporting financial information. Net income increased from approximately VND483 billion in 2022 to VND679.4 billion in 2025, bringing four-year cumulative profit to nearly VND2.35 trillion.
At year-end 2025, equity reached nearly VND2.884 trillion, up approximately 30%. The company also eliminated VND1.4 trillion of outstanding bonds while bank borrowings rose to roughly VND2.415 trillion. Total liabilities nevertheless declined by more than 4%, reducing the debt-to-equity ratio from 1.91x to 1.40x.
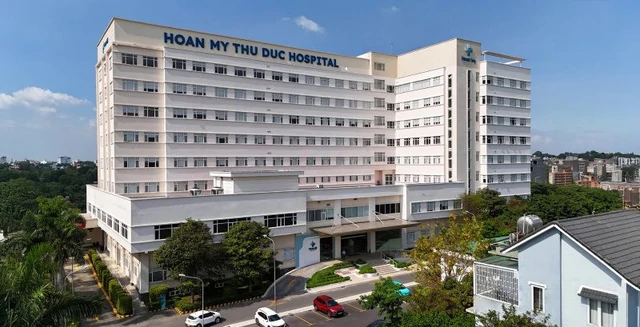
Operationally, Hoan My currently runs 14 hospitals and two clinics, with around 2,900 operating beds, more than 5,500 employees and over six million patient visits annually across brands including Hoan My, Hoan My Gold, Hanh Phuc and Thuan My. The network is part of Singapore-headquartered Clermont Group.
Why It Matters
- Private-hospital scale is beginning to create economic leverage. A large network can centralize procurement, IT, clinical protocols, marketing, workforce development and back-office functions instead of replicating them hospital by hospital.
- Consolidation improves access to capital. Stable profitability and a larger equity base make it easier to finance new equipment, specialty services, digital infrastructure and acquisitions.
- Multi-brand architecture enables patient segmentation. A network can serve value-oriented and premium patients through different brands rather than forcing every facility into a single price and service proposition.
- Balance-sheet quality matters alongside profit. Eliminating bond debt reduces one refinancing risk, although the sharp increase in bank borrowing deserves continued monitoring.
Healthcare Insight Analysis
Healthcare Insight believes the VND2.35 trillion figure is best viewed as evidence of maturing private-hospital platform economics, rather than simply a story about hospitals generating large profits.
Hospitals are inherently fixed-cost businesses.
Buildings, advanced equipment, operating theatres, intensive care, 24-hour staffing and regulatory systems must all be maintained even before beds are fully utilized.
For a standalone hospital, underutilization can therefore destroy returns quickly.
A network changes that equation.
A 14-hospital system can potentially negotiate drug and device purchasing centrally, share specialist expertise, coordinate referrals, build a national brand and concentrate selected complex services into particular hubs rather than reproducing every capability at every site.
That is where healthcare scale economics emerge.
Hoan My has also used acquisitions as an important scaling mechanism. After joining the Clermont ecosystem in 2013, the network continued to expand and later acquired Hanh Phuc International Hospital, adding premium maternal and pediatric care to its multi-brand portfolio.
However, current profit numbers should not be treated as proof that every network synergy has already been realized.
The disclosed information focuses largely on profit, assets, equity and liabilities. It does not provide enough detail on revenue growth, EBITDA margin, occupancy, revenue per bed, payer mix or same-hospital performance to determine whether the 2025 earnings improvement came mainly from higher patient volumes, pricing, case-mix improvement, acquisitions or cost efficiencies.
That distinction matters for investors.
The debt profile also deserves attention. Hoan My repaid VND1.4 trillion of bond principal during 2025, but bank loans rose to more than VND2.4 trillion.
That is not necessarily negative. Bank financing may offer greater flexibility. But it reinforces a fundamental point: hospital growth remains capital intensive even when the platform is profitable.
Market Implications
Hospital groups: future advantage increasingly lies in network density, clinical standardization and referral ecosystems rather than owning a single flagship facility.
Investors: scaled healthcare platforms can offer recurring demand and stronger cash-generation potential, but valuation should depend on operating metrics rather than headline profit alone.
Pharma and medtech: larger networks bring greater purchasing power, yet also create the opportunity to access multiple hospitals through enterprise-level relationships.
Independent hospitals: competition may become tougher as scaled networks combine brand recognition, capital, digital infrastructure and stronger physician recruitment capabilities.
ANALYTICAL MATRIX
| Dimension | Current Signal | Strategic Value | Key Risk |
|---|---|---|---|
| Scale | 14 hospitals, 2 clinics, ~2,900 beds | Procurement and referral leverage | Multi-site management complexity |
| Profitability | ~VND2.35tn over four years | Internal capital for reinvestment | Underlying growth drivers remain unclear |
| Capital structure | VND1.4tn bond debt eliminated | Lower refinancing exposure | Bank borrowing rose sharply |
| Multi-brand model | Hoan My, Hanh Phuc, Thuan My, Hoan My Gold | Patient and price segmentation | Brand overlap and operational fragmentation |
The next two metrics worth watching are revenue or EBITDA per bed, and same-hospital growth rather than expansion driven primarily by acquisitions.
If Hoan My can continue improving both while maintaining disciplined leverage, the story becomes larger than one profitable hospital company: it would demonstrate that healthcare consolidation in Vietnam is becoming a scalable, compounding business model.